The Short Answer
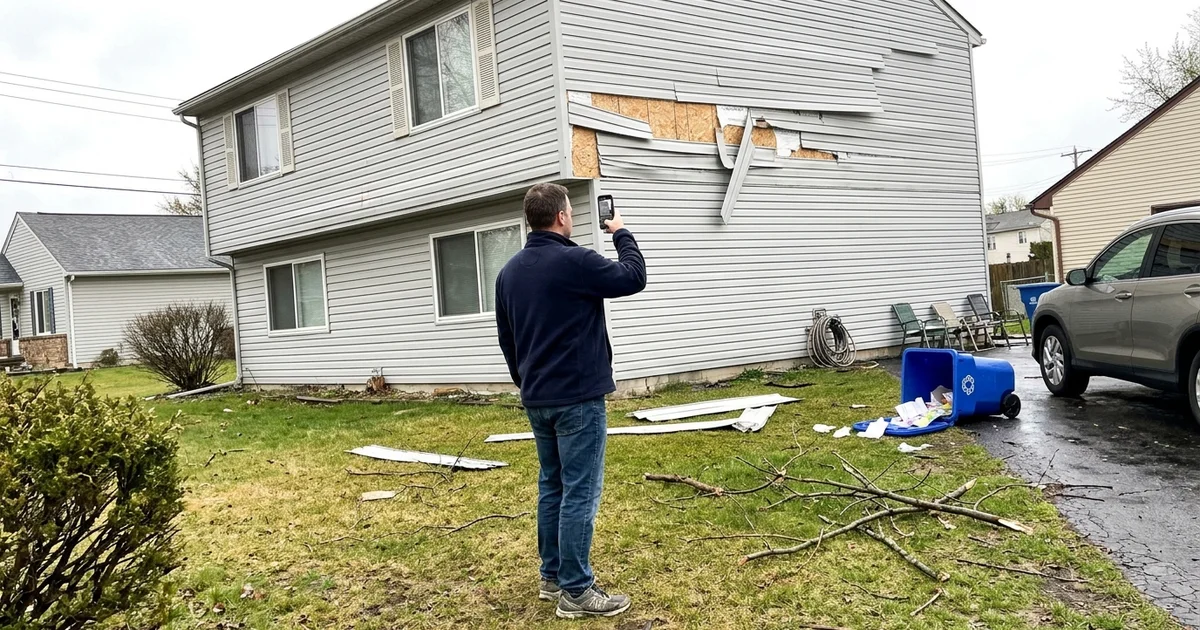
Often, yes, but it depends on your policy. If you’re asking whether insurance covers siding storm damage, sudden harm from wind, hail or a falling tree limb is commonly covered. Wear and tear, old age and slow damage usually aren’t.
Michigan storms make this a real question. In March 2026, four tornadoes hit the state, including its earliest-ever EF-3, according to Insurance Business. State Farm reported hundreds of claims within days.
Your deductible, your policy type and how your insurer handles matching all affect what you actually get. Business owners should read their commercial property policy instead, since the wording often differs from a homeowners policy.
We’re siding contractors, not insurance agents, so this guide stays general. Coverage depends on your policy, and we don’t file claims for you. What we do as part of our storm damage siding repair service is give you clear photos and a written estimate you can share with your insurer.
Important
Coverage depends on your policy. Read it, and ask your insurer or agent. We don’t file claims or negotiate with insurers.
Sudden Storm Damage vs. Wear and Tear
Most homeowners policies cover damage that happened suddenly and exclude damage that built up over time. Progressive describes it this way: siding is typically covered when a covered peril causes the damage, and general wear and tear is typically not.
| Usually treated as sudden damage | Usually treated as wear and tear |
|---|---|
| Siding blown off in a wind storm | Faded or chalky vinyl |
| Hail cracks and dents | Siding that’s brittle from age |
| Holes from a falling branch | Rot from long-term leaks |
| Panels torn loose by debris | Peeling paint and stain |
Old, brittle siding is where claims get tricky. An adjuster may look at whether the storm caused the damage or just finished off siding that was near the end of its life. If yours was already worn out, our guide to siding repair vs. replacement can help you weigh a patch against a full reside.
That’s one reason clear photos of the damage, taken soon after the storm, matter so much. Hail claims are common, too. According to the Insurance Information Institute (Triple-I), about one in 36 insured homes has a wind or hail claim each year.
Deductibles Matter
Your deductible is what you pay before insurance pays anything. If the repair is a few cracked panels, the cost may be close to or under your deductible, and a siding insurance claim may not be worth filing. If siding is torn off several walls, the math looks different.
Some policies have a separate deductible for wind or hail. Triple-I says these usually run between 1 and 5 percent of your home’s insured value, not a flat dollar amount. Here’s what that looks like on a home insured for $300,000:
| Wind/hail deductible | What you pay first |
|---|---|
| 1% | $3,000 |
| 2% | $6,000 |
| 5% | $15,000 |
Westfield Insurance uses the same 1% example to show how a percentage deductible can end up higher than your standard one. Check your declarations page or ask your agent so there are no surprises.
Questions to Ask Your Insurer
Before you file, or right after, it helps to ask:
- Is wind and hail damage to siding covered under my policy?
- What’s my deductible for this kind of damage?
- Does my policy pay replacement cost or actual cash value?
- How do you handle matching? If replacement siding can’t match what’s on the house, what does my policy do?
- Do you need photos, a contractor estimate, or both?
- Is there a time limit to report storm damage?
Question 3 changes your check more than most people expect. Country Financial explains that actual cash value is replacement cost minus depreciation, so it typically pays less than replacement cost.
| Replacement cost | Actual cash value | |
|---|---|---|
| Depreciation deducted? | No | Yes |
| Typical payout | Higher | Lower |
On question 6, Weather Vane Roofing notes that most Michigan homeowners policies require a claim within one year of the loss, and some allow two. Your declarations page has the real answer for your policy, so check it early.
Why Matching Is the Question People Forget
Siding fades, and colors get discontinued. Policies handle it differently, so ask how yours does.
No single federal siding matching law exists, according to Vector Claim Solutions. The National Association of Insurance Commissioners (NAIC) has a model regulation that addresses matching, but each state decides whether and how to apply it. Peak Home Exteriors, a Michigan contractor, reports that Michigan has no specific statute requiring insurers to match siding, so your policy language carries the weight.
Vector Claim Solutions says dated photos and written proof that matching siding is no longer available carry the most weight. Ask your insurer about this before the repair starts.
Documentation to Keep
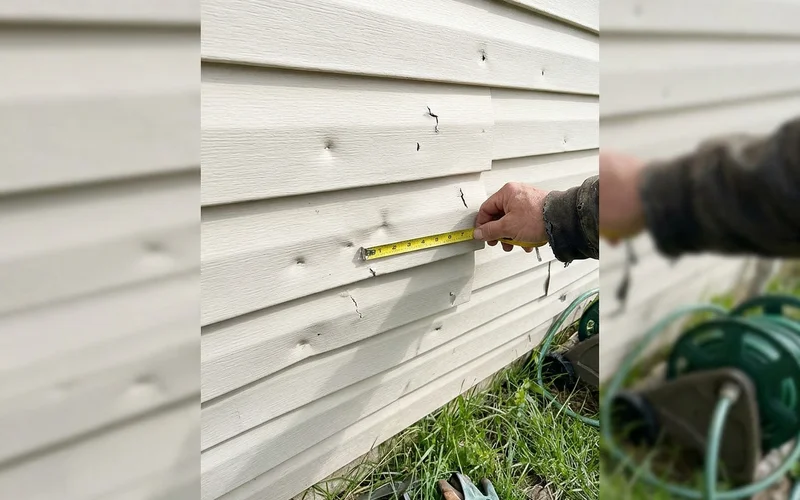
Good records make any claim easier, especially a hail damage siding insurance claim where the dents can be subtle. After a storm:
- Take photos from the ground as soon as it’s safe. Get wide shots of each side of the house and close-ups of damage. Put something in the frame for scale, like a tape measure.
- Note the date and time of the storm.
- Keep any pieces of siding or trim that came off.
- Save receipts for anything you do to protect the house, like tarping you do yourself where it’s safe.
- Get a written repair estimate that lists the damaged areas and what it takes to fix them.
Don’t climb ladders or go on the roof after a storm. Photos from the ground are enough to start.
If your claim is denied or drags on, the Michigan Department of Insurance and Financial Services (DIFS) can help. Its consumer call center is 877-999-6442, open Monday through Friday from 8 a.m. to 5 p.m., according to a April 2026 DIFS release.
What We Do, and What We Don’t
When you call us after a storm, we:
- Schedule your estimate as quickly as we can
- Look at the damage up close and photograph it
- Give you a written estimate of the repair that you can share with your insurer
- Repair the siding and check the wrap behind it so the wall is closed up again
We don’t file claims, talk to your insurer on your behalf, promise what your policy covers, or offer emergency tarping or board-up.
One tip from insurance.com: a single storm often damages the roof, windows and siding together, and insurers commonly handle those as one claim. Tell us which walls took hits, and we’ll photograph each one so your records match what you report.
Next Steps After a Storm
Stay safe first. Take your photos, call your insurer to ask about coverage, and get a repair estimate so you know what you’re dealing with.
Whether or not you file a claim, an open wall lets water in, so it’s worth getting it closed up. Knowing the answer to “does insurance cover siding storm damage” for your own policy starts with that call and a written estimate.
Request a free estimate and our Grand Rapids siding contractor team will take a look.